Green finance means capital that is deliberately steered toward projects with an environmental benefit: renewable power, grid upgrades, efficient buildings, clean transport, water systems. In 2026 it is no longer a niche. Cumulative issuance of sustainable debt aligned with Climate Bonds Initiative criteria reached USD 6.8 trillion by the end of 2025. Annual issuance passed USD 1 trillion for the third year running.
That scale still falls short of what climate targets require. The Climate Policy Initiative put global climate finance flows at about USD 2 trillion in 2024. It estimates average annual mitigation finance must reach roughly USD 7.8 trillion between 2025 and 2030. The gap is the opportunity.
At the same time, the rulebook changed sharply. The EU cut the number of companies that must publish sustainability reports. The US securities regulator moved to scrap its climate disclosure rule entirely. A well-known “green” bank collapsed in a fraud case. This guide covers what actually holds up in 2026: the instruments you can buy, the standards worth checking, the rules that now apply, and the risks that cost investors money.
Key Takeaways
- Market scale: Aligned sustainable debt reached USD 6.8 trillion cumulatively by end-2025, with green bonds making up 64% of 2025 issuance.
- Persistent gap: Climate finance flows of roughly USD 2 trillion a year sit well below estimated needs.
- Rules loosened in the EU: The Omnibus I package cut CSRD reporting to companies above 1,000 employees and EUR 450 million turnover.
- Rules stalled in the US: The SEC proposed full rescission of its climate disclosure rule in May 2026.
- Verification matters more, not less: With mandatory reporting narrowed, labels, second-party opinions and post-issuance reports carry more weight.
Climate finance, green finance and sustainable finance: what the terms actually mean
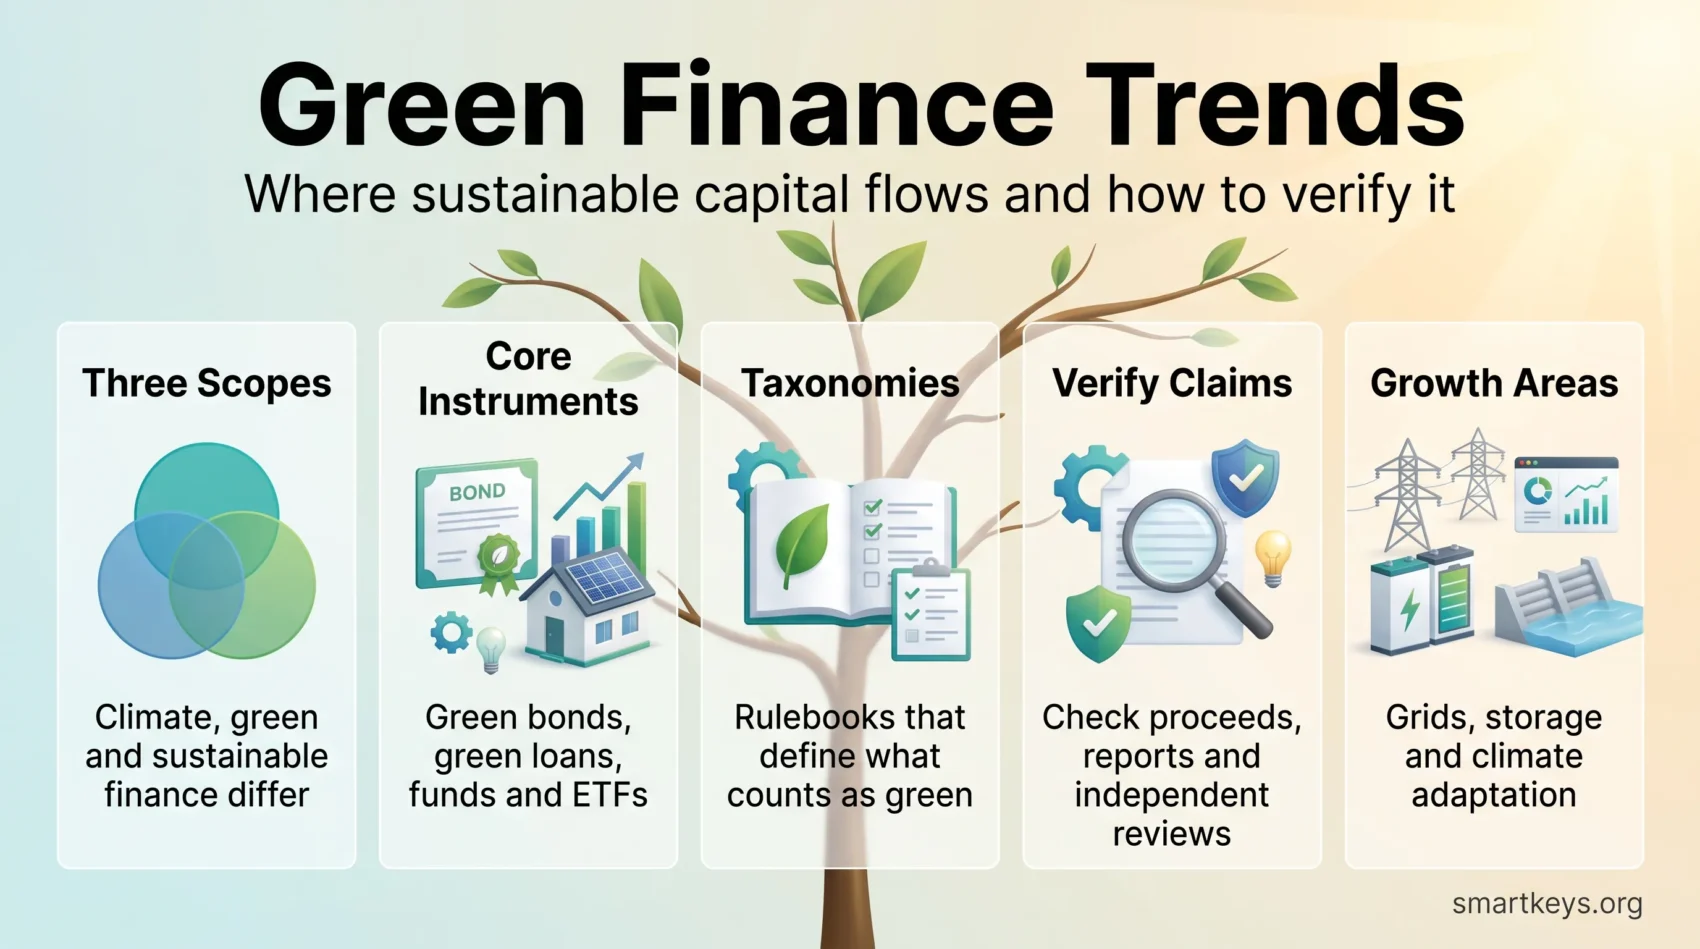
These three labels get used interchangeably, and that costs people money. They describe different scopes, and the scope decides which rules, tax breaks and reporting duties apply.
Climate finance is the narrowest. It funds cutting emissions (mitigation) or coping with climate impacts (adaptation). A wind farm loan and a flood defence grant both qualify.
Green finance is broader. It covers environmental goals generally, including water quality, pollution control and biodiversity. A wastewater treatment upgrade is green finance but not strictly climate finance.
Sustainable finance is broadest of all. It adds social and governance factors to the environmental ones, which is what people mean by ESG. A bond that funds affordable housing sits here, not under green finance.
Within sustainable finance, three approaches often get confused:
- ESG integration folds environmental, social and governance data into ordinary financial analysis. The goal is better risk-adjusted returns, not impact.
- Impact investing targets a measurable environmental or social outcome alongside a return, and reports on it.
- Ethical investing screens out what you do not want to own, such as tobacco or thermal coal.
Getting the label right is practical. It decides eligibility for a bond standard, the disclosures you owe, and whether a regulator can accuse you of overstating your claims. If you are setting internal definitions, an ESG framework built around clear goals and owners is the place to start.
The policy anchor behind all of it is Article 2.1(c) of the Paris Agreement. It commits signatories to make financial flows consistent with low-emission, climate-resilient development. That single clause is why central banks, taxonomies and disclosure rules exist at all.
How big is the green finance market in 2026?
The market grew from a rounding error to a mainstream asset class in about a decade.
The current numbers
Climate Bonds Initiative data for 2025 gives the clearest picture of labelled debt:
- Cumulative aligned issuance: USD 6.8 trillion by the end of 2025.
- Green bonds in 2025: USD 653.5 billion, or 64% of aligned issuance that year.
- Sustainability bonds: USD 217.3 billion. Social bonds: USD 141.2 billion.
- Sustainability-linked bonds: USD 14 billion, up 46% year on year from a small base.
- Regional split: Europe accounted for 45% of aligned annual volume. Asia-Pacific issued USD 305.6 billion.
Funds tell a similar story. Morningstar counted USD 3.7 trillion in global sustainable fund assets at the end of the second quarter of 2026, with Europe holding USD 3.1 trillion of that, or 84%. Net inflows were positive but modest at USD 3.7 billion for the quarter. The money is invested; it is not surging in.
What keeps the market growing
Three forces sustain demand, and none of them depends on sentiment.
First, energy economics. Solar and battery costs fell far enough that new renewable capacity competes on price in most markets, which makes many projects bankable without subsidy. Green technology trends shape which of those projects reach financial close.
Second, physical need. Grids, storage and water infrastructure require capital on a multi-decade schedule regardless of the political cycle.
Third, mandated flows. Central bank frameworks, national taxonomies and institutional mandates route capital toward eligible assets whether or not individual investors want them to.
Where the opportunities sit
Capital concentrates in renewable generation, transmission and storage, building efficiency retrofits, electrified transport and charging, and water. Adaptation projects, meaning flood defence, drought resilience and nature-based solutions, remain underfunded relative to mitigation. That imbalance is a signal for investors willing to underwrite less crowded risk. Broader climate tech funding patterns show where private capital is concentrating within these categories.
Green finance products you can actually use
The instrument you choose depends on whether you are financing something, investing in something, or both.
Green loans and mortgages
Some lenders price efficiency into the loan. NatWest in the UK offers a reduced rate on two-year and five-year fixed mortgages when the property holds an Energy Performance Certificate rating of A or B. The maximum loan-to-value is 85%. US lenders structure comparable products for electric vehicles and efficiency retrofits.
Before you apply, check whether the discount survives the product fees, and whether the lender demands evidence of the efficiency rating.
Green banks and blended finance
A green bank uses public money to lower the cost of private capital for clean energy projects that commercial lenders would otherwise decline. Several US states run one. The mechanism is blended finance: public funds absorb the first losses or the early-stage risk, which brings private investors into deals they would not fund alone.
This matters most for small and distributed projects, such as community solar or municipal efficiency upgrades, where transaction costs are high relative to deal size.
Funds and ETFs
Listed funds are the simplest route for most investors. The work is in vetting them, not buying them. Look at three things:
- The index methodology. What does the fund actually exclude, and what does it merely underweight?
- Engagement record. Does the manager vote its shares and escalate when companies miss targets, or does it hold passively?
- Holdings, not the name. Fund names are marketing. Portfolios are evidence.
Green bonds: how they work and what to check
A green bond is an ordinary bond with a promise attached. The issuer commits to spending the proceeds on eligible environmental projects and to reporting on that spending afterwards. The credit risk is the issuer’s credit risk; the green label does not improve it.
Use-of-proceeds bonds versus project bonds
Most green bonds are use-of-proceeds bonds. The issuer raises money against its balance sheet and allocates it to a pool of eligible projects. If the issuer defaults, you are a general creditor, not a claimant on the wind farm.
Project bonds ring-fence specific assets. Repayment comes from that project’s cash flows. Security is clearer and reporting is tighter, but you carry concentrated project risk instead of diversified issuer risk.
Standards and the European Green Bond label
Two voluntary standards dominate: the ICMA Green Bond Principles, which set process expectations, and Climate Bonds Initiative certification, which applies sector-specific technical criteria.
The European Green Bond Regulation added a stricter option. It entered into force on 21 December 2024. Issuers may use the protected “EuGB” designation only if proceeds align with the EU taxonomy and an external reviewer signs off. Uptake has been real but selective. IEEFA reported more than EUR 22 billion of EuGB-labelled issuance in the standard’s first year, concentrated among grid operators and renewable energy utilities, as of February 2026.
The label is strict by design. Many issuers find full taxonomy alignment too demanding for their project pipeline and stay with the looser ICMA framework instead.
Pricing and the greenium
Strong demand can push labelled bonds to slightly tighter yields than an identical conventional bond from the same issuer. Market participants call this the greenium. It is small, varies by issuer and currency, and is not reliable enough to build a strategy around. Treat it as a modest cost of holding the label, not as evidence of quality.
Before you buy, confirm:
- Which project categories the proceeds may fund, in writing.
- Whether a second-party opinion exists and who issued it.
- Whether the issuer publishes allocation and impact reports after issuance, and whether past ones were actually delivered.
Central banks and the policy machinery behind the market
Supervisors shape this market more than most investors realise. Their decisions affect capital requirements, collateral eligibility and ultimately what a project costs to finance.
The Network for Greening the Financial System, known as the NGFS, is the main coordinating body. It is a voluntary grouping of central banks and financial supervisors founded in 2017. As of 26 August 2026 it had 152 members across more than 95 countries plus 24 observers. Its climate scenarios have become the default reference for stress testing bank and insurer balance sheets.
Membership is not universal. The US Federal Reserve withdrew in January 2025, stating that the network’s scope had moved beyond the Fed’s statutory mandate. That split matters: it means US and European banks increasingly face different supervisory expectations on climate risk.
The European Central Bank has gone furthest in practice. It has incorporated climate criteria into its corporate bond holdings and its collateral framework, which changes what banks can pledge and on what terms. Three tools are worth watching because they change borrowing costs directly:
- Collateral rules: preferential treatment for eligible assets makes them cheaper to fund.
- Asset purchases: tilting purchases toward lower-emission issuers shifts relative spreads.
- Supervisory expectations: capital and provisioning treatment influences what banks are willing to lend against.
Central bank communications usually arrive before market pricing adjusts. Reading them early is one of the few free information advantages available here. The same logic applies to other financial rule changes, such as the shift in open banking rules.
Disclosure in 2026: what changed and what still applies
This is where the picture shifted most since 2024. Reporting obligations narrowed in both the EU and the US, though for different reasons.
TCFD is gone; its structure survives
The Task Force on Climate-related Financial Disclosures, or TCFD, published the four-pillar framework most climate reporting still follows: governance, strategy, risk management, and metrics and targets. The task force itself was disbanded at COP28 in December 2023, and monitoring responsibility passed to the International Sustainability Standards Board from 2024.
The framework did not disappear. It was absorbed. IFRS S2, the ISSB climate standard, carries the same four pillars forward. If your company already reports against TCFD, the structure of your disclosure remains valid; the standard it points to has changed name.
CSRD after Omnibus I
The Corporate Sustainability Reporting Directive was originally set to cover tens of thousands of EU companies. The Council of the European Union adopted the final Omnibus I simplification text on 24 February 2026, and the scope is now much narrower.
Under the revised rules, a company must report only if it exceeds both thresholds: more than 1,000 employees and more than EUR 450 million in net annual turnover. Companies that reported in the first wave but now fall outside the scope get a transition exemption for 2025 and 2026.
The related Corporate Sustainability Due Diligence Directive was narrowed further still, to companies above 5,000 employees and EUR 1.5 billion in turnover. The mandatory climate transition plan requirement was removed, and civil liability was capped at 3% of net worldwide turnover. Member states must transpose the changes by 26 July 2028, with compliance required from July 2029.
If your company dropped out of scope, the reporting duty ended but the demand for the data did not. Lenders, large customers and index providers still ask for it. Many firms now keep carbon accounting systems running voluntarily because their counterparties require the numbers.
The US position
The SEC adopted a climate disclosure rule in March 2024, then stayed it in April 2024 pending litigation. It never took effect. In March 2025 the Commission stopped defending it in court, and on 29 May 2026 it proposed rescinding the rule entirely, citing cost and burden.
For US companies, that removes a federal reporting obligation but not state-level ones, and not the requirements that follow from operating in or selling into the EU. Voluntary disclosure remains the norm among large listed issuers, driven by investor demand rather than regulation. Companies that treat this as a risk management question rather than a compliance question tend to keep reporting either way.
Taxonomies: the rulebook for what counts as green
A taxonomy is a classification system that says, in technical detail, which economic activities count as environmentally sustainable. Without one, “green” means whatever the seller says it means.
The EU taxonomy, in force since 2020, is the most developed. It tests an activity against six environmental objectives: climate change mitigation, climate change adaptation, sustainable use of water and marine resources, transition to a circular economy, pollution prevention, and protection of biodiversity and ecosystems.
To qualify, an activity must clear three hurdles:
- Substantial contribution to at least one of the six objectives, measured against technical screening criteria.
- Do No Significant Harm to any of the other five.
- Minimum safeguards on labour and human rights.
Why gas and nuclear caused a fight
The Commission’s decision to include some fossil gas and nuclear activities under conditions drew sustained criticism, including from its own technical advisers. The objections centred on methane leakage from gas supply chains and on unresolved waste questions for nuclear.
The dispute is not abstract for investors. Index providers and fund managers took different positions on whether to follow the taxonomy on this point, so two funds that both claim taxonomy alignment can hold materially different assets.
Fragmentation is the real cost
The UK, Singapore, China, Mexico and others have built or are building their own taxonomies. Some align closely with the EU version; others diverge on transition activities. For an issuer operating across borders, that means mapping the same project against several rulebooks. It is a compliance cost that scales badly, and it is one reason RegTech tools that automate controls mapping have found buyers in this space. Similar cross-border data problems appear in data localization rules, where one product meets several incompatible regimes.
US programs that finance green projects
Federal support in the US runs mostly through state-administered revolving loan funds rather than direct grants.
The Clean Water State Revolving Fund is the largest route for water infrastructure. Each state runs its own fund and lends at below-market rates for wastewater treatment, stormwater management and related work. Funding levels moved in 2026: Congress appropriated USD 746.1 million in regular appropriations plus USD 2,603.0 million from the infrastructure law, for a total of USD 3,349.1 million in FY2026. That is down from USD 4,241.9 million in FY2025, with the reduction falling on the regular appropriation rather than the infrastructure tranche.
The practical implication is that state programs are more oversubscribed than they were. Applications succeed on preparation, not enthusiasm. Engage your state program manager before you write the proposal, have the engineering assessment finished, and state the water quality outcome in measurable terms.
The Small Business Administration offers loan guarantees that small firms can use for efficiency and clean technology investments. There is no separate “green” product; you use standard SBA loan programs and make the business case on payback.
Stacking works. A low-interest state revolving fund loan alongside private debt lowers your blended cost of capital and often makes an otherwise marginal project viable.
Deploying capital: a practical approach
Start with what you need the money to do, then pick instruments, not the other way round.
For liquidity and simple exposure: listed green bond funds and climate ETFs. You can size and exit positions easily, and you accept whatever the index methodology gives you.
For yield and duration: individual labelled bonds or private credit in infrastructure. Longer commitment, better spread, more diligence required.
For direct influence: project equity or blended structures. You get a seat at the table on how the asset is run, and you carry development risk.
Whatever the mix, write down what you expect it to achieve before you invest. Two metrics are enough: a financial one and an environmental one you can actually source. Vague targets are how portfolios end up with expensive holdings that satisfy nobody at review time.
Stewardship is the part most investors skip. Voting your shares changes company behaviour more reliably than screening, which just transfers them to a less demanding owner.
Managing risk: transition, policy and greenwashing
Three risks dominate here, and they interact.
Transition risk is the chance that an asset loses value because technology, policy or demand shifts against it. A gas peaker plant with a 25-year payback is a transition risk question, not an engineering one.
Policy risk cuts both ways in 2026. Investors spent years pricing in tightening rules. The EU simplification package and the SEC rescission proposal show that rules can loosen too, which changes the value of compliance investments already made.
Greenwashing risk is the one that produces losses fastest.
What greenwashing costs: the Aspiration case
Aspiration was a US neobank built entirely on an environmental proposition, including tree planting tied to customer spending. It filed for Chapter 11 bankruptcy in March 2025. Co-founder Joseph Sanberg pleaded guilty to wire fraud, admitting he defrauded investors and lenders of at least USD 248 million between January 2021 and December 2022, and was sentenced to 14 years. The SEC alleged he raised more than USD 300 million partly on the basis of fabricated revenue from environmental sustainability services. KPMG had resigned as auditor in July 2022, citing transactions with characteristics of fraud.
The lesson is not that green branding signals fraud. It is that an environmental story can substitute for financial scrutiny if you let it. The auditor’s resignation was a public warning nearly three years before the bankruptcy.
A practical screen:
- Read the use-of-proceeds language, not the brochure. Vague categories mean vague obligations.
- Check whether post-issuance reports were actually published on schedule, not just promised.
- Ask who reviewed the claims and whether that reviewer is independent of the issuer.
- Treat auditor resignations, restatements and unexplained management departures as disqualifying until explained.
- Compare the environmental claim against the capital expenditure. Spending shows intent more honestly than a strategy document.
The same discipline applies across sustainability claims generally, whether you are assessing a fund, a supplier or your own sustainability strategy. And it now has a legal edge in the EU, where new rules restrict unsubstantiated environmental marketing claims. What consumers actually reward turns out to be narrower than most marketing assumes.
Financed emissions: the number that dominates a lender’s footprint
If you run a bank, an insurer or an investment fund, the emissions from your offices and travel are close to irrelevant. What matters is the emissions of what you lend to and invest in. These are called financed emissions.
CDP’s 2021 analysis of the financial sector found that portfolio emissions were on average more than 700 times larger than institutions’ own operational emissions. The ratio has not been superseded by a more recent comparable study, and it explains why supervisors focus on portfolios rather than premises.
The standard measurement method comes from the Partnership for Carbon Accounting Financials, known as PCAF. It attributes a share of each borrower’s or investee’s emissions to you, based on your share of their financing. The method also grades data quality on a five-point scale, so a portfolio number carries an honest confidence marker with it.
Building the number in practice takes three steps:
- Get position-level data first. Actual reported emissions from the borrower beat any estimate.
- Use proxies for the gaps, based on sector and revenue, and record that you did.
- Set controls and an audit trail, because the number will eventually be challenged by someone.
Once you have it, the number is only useful if it changes decisions: which sectors you grow, which clients you engage, and where you reprice. A measurement that never reaches the credit committee is an expense, not a capability. Good data governance is the difference between a figure you can defend and one you cannot.
Green finance trends shaping the next decade
Five developments look durable enough to plan around.
Grid and storage take the largest share. Generation capacity outpaced transmission capacity in most markets, and connection queues are now the binding constraint. Capital is rotating toward the wires and batteries that let existing generation actually reach customers.
Adaptation finance grows from a small base. Water security, flood defence and heat resilience attract capital as physical losses mount. This segment is less crowded than renewable generation and priced accordingly.
Verification replaces volume as the growth story. With mandatory reporting narrowed in both major markets, voluntary credibility becomes the differentiator. Expect more demand for third-party assurance, not less.
Supply chains enter the calculation. Minerals, components and manufacturing capacity constrain energy projects and create their own environmental exposures. Greener supply chains and supply chain resilience are becoming underwriting questions rather than procurement questions. The EU’s digital product passport will make some of that data mandatory at product level.
Corporate transition finance broadens the universe. Sustainability-linked instruments tie pricing to the borrower’s own targets rather than to a project. That opens financing to heavy industry, where there is no clean asset to ring-fence but a large emissions reduction to fund. It also creates the widest scope for weak targets, so the covenant language matters more than the label.
Related shifts worth tracking include ESG reporting software and the emissions of the cloud itself, the evolving corporate responsibility reporting landscape, and how carbon neutrality commitments translate into actual capital expenditure. For practical strategy and software guidance, see this ESG SaaS playbook. For operational checks on transactions, see this taxonomy-aligned transaction guide.
Conclusion
Green finance in 2026 is a large, liquid market operating under a lighter regulatory hand than most people expected two years ago. The EU narrowed its reporting requirements and the US moved to drop its climate rule. Neither change reduced the capital needed or made verification less important.
That combination puts more weight on your own diligence. Read use-of-proceeds language rather than fund names. Check whether promised reports were actually filed. Measure financed emissions with a method that grades its own data quality. Stack public and private capital where the economics are marginal.
The gap between roughly USD 2 trillion flowing each year and the several trillion the transition requires is not going to close on sentiment. It closes on projects that pencil out, and on investors who can tell the difference between a labelled bond and a credible one.
Found this useful?
Make SmartKeys a preferred source on Google, and our articles will surface more often in your Top Stories, AI Overviews, and AI Mode.
Add as Preferred Source