Vertical SaaS means cloud software built for one industry instead of all of them. A booking system made only for dental practices is vertical SaaS. A general calendar app that any business can use is not.
That distinction has turned into one of the more reliable growth stories in business software. Mordor Intelligence values the vertical software market at about $164 billion in 2026 and expects it to reach roughly $283 billion by 2031, a compound annual growth rate of 11.5%. Compound annual growth rate, or CAGR, is simply the average yearly growth needed to get from the first number to the last.
This guide explains what industry-specific software is, why buyers keep choosing it, how the winners built their businesses, and which sectors look most promising in 2026. It is written for founders, operators and buyers rather than for analysts, so every term gets explained the first time it appears.
Key Takeaways
- Vertical SaaS is software shaped around one industry’s workflows, vocabulary and compliance rules.
- The market is growing at roughly 11.5% a year through 2031, faster than software overall.
- Buyers pick it because it works out of the box, not because it has more features.
- Payments and other financial services are often the biggest revenue source, not the software fee.
- AI helps most when it runs on the industry data a vendor already holds.
- Construction, manufacturing, healthcare, agriculture and property look like the strongest 2026 sectors.
What vertical SaaS actually means
SaaS stands for software as a service: software you rent through a browser instead of installing and maintaining yourself. Horizontal SaaS serves any industry, so think of a spreadsheet tool, a chat app or a general reporting tool. Vertical SaaS serves one, and ships with that industry’s rules already built in. Well-known examples include Veeva Systems for pharmaceutical and life sciences companies, Procore for construction firms and Guidewire for insurers.
Industry-specific workflows, compliance and integrations explained
A product built for a single sector arrives preconfigured. The screens use the words the staff already use. The required fields match the regulator’s forms. The reports are the ones the finance team files anyway.
A veterinary clinic system, for example, knows what a vaccination schedule is, links it to a species and breed, and prints the reminder the practice is legally required to send. A general appointment tool has to be bent into that shape by whoever sets it up.
- Faster to launch: prebuilt connections and industry defaults cut the setup work.
- Less training: staff recognize the process, so adoption is quicker.
- Fewer compliance gaps: the checks that matter in that sector are already there.
- A real trade-off: you still need to connect the product to payroll, accounting and email.
Most companies end up running both kinds. They use a specialist product for the work that defines their business, and general platforms for everything else. That mix is normal and usually cheaper than forcing one tool to do everything, though it does put weight on your integration layer.
Why buyers keep choosing specialist software
The commercial effect shows up in three places. Sales cycles are shorter, because the demo already speaks the buyer’s language. Churn is lower, because the product sits inside a daily process rather than beside it. And expansion is easier, because a vendor who understands the work can see the next problem worth solving.
From niche curiosity to serious category
Ten years ago industry software was often dismissed as a small market with a low ceiling. Two things changed that. Buyers grew tired of stitching general tools together and paying someone to maintain the joins. And the large cloud providers started shipping industry cloud platforms, meaning industry versions of their own products. That made the category look less risky to committee buyers.
“A narrow market is only a disadvantage if you cannot take a large share of it.”
The catch is that a smaller total market leaves less room for error. If you own a niche, growth has to come from selling more per customer rather than from finding endlessly more customers.
Built for teams that are not in one office
A lot of industry work happens away from a desk. Think of service technicians, site managers, home care nurses or insurance adjusters on the road. General collaboration suites keep these people talking through chat, video and shared files. They do not know what a work order, a site diary or a patient record is, though.
A vertical product puts that industry record on the phone of the person doing the job, with the same rules that apply in the office. Compliance travels with it. In US healthcare, for example, any software that stores patient data has to support HIPAA, the federal privacy law for health information. A specialist vendor usually signs the required agreement and ships the access controls by default. With a general tool, that setup is your job.
The practical test for distributed teams is simple: can someone complete the core task on a phone, in poor signal, without calling the office? If not, the product is not really built for how the industry works.
The forces reshaping industry software in 2026
Three things are pushing this market along right now.
Tool sprawl. Companies accumulate apps, and each one adds a login, an export and a place for data to go stale. Replacing several general tools with one that covers the whole process is an easy saving to explain to a finance director.
Digitization of stubborn sectors. Industries that ran on paper, phone calls and spreadsheets are finally moving. That is where the unmet demand sits, and it is why the fastest-growing niches are rarely glamorous ones.
Money and intelligence inside the product. Two additions changed the economics of these businesses: embedded finance, which means offering payments, payouts or lending inside the software itself, and AI features trained on the vendor’s own industry data. Both turn a subscription into something closer to infrastructure.
Trading market size for market share
A vertical vendor deliberately picks a smaller pond. The bet is that deep fit lets you win a large share of it and then sell several products to the same customer, rather than one product to many customers who are only loosely interested. That is the same logic behind micro-SaaS products, just at a larger scale.
AI: from system of record to system of intelligence
A system of record is software that stores what happened: the appointment, the invoice, the inspection. A system of intelligence uses that stored history to suggest what should happen next.
Industry vendors are unusually well placed for this, because they hold structured data that general models never see. A field service platform knows which fault codes precede a failure on which equipment. That is the raw material for a useful prediction.
What the evidence says about returns
It is worth being honest about how much of this is delivering. McKinsey’s State of AI survey published in August 2026 found that 37% of organizations attribute at least some effect on operating profit to their AI use, roughly flat on the year before, and that only 6% qualify as high performers. Among companies with more than $1 billion in revenue, 40% are scaling AI agents, up from 27% a year earlier, and 80% of people using AI say it makes them personally more productive.
The gap between personal productivity and company profit is the story of enterprise AI in business right now. Narrow, well-scoped features on proprietary data are the ones most likely to close it.
Where AI earns its place in a vertical product
- Forecasting: demand, no-shows, equipment failure, staffing levels.
- Next best action: surfacing the one thing a user should do now.
- Industry language: search and assistants that understand the sector’s jargon and abbreviations.
- Document handling: pulling structured data out of the forms a sector still runs on.
Two constraints apply. Users need to see why a system suggested something, or they will not trust it. And in the European Union, the EU AI Act now imposes transparency duties on AI features that interact with people, so disclosure is part of the product, not an afterthought.
The growth playbook that works
The pattern behind most successful industry platforms is consistent.
Start narrow, then expand
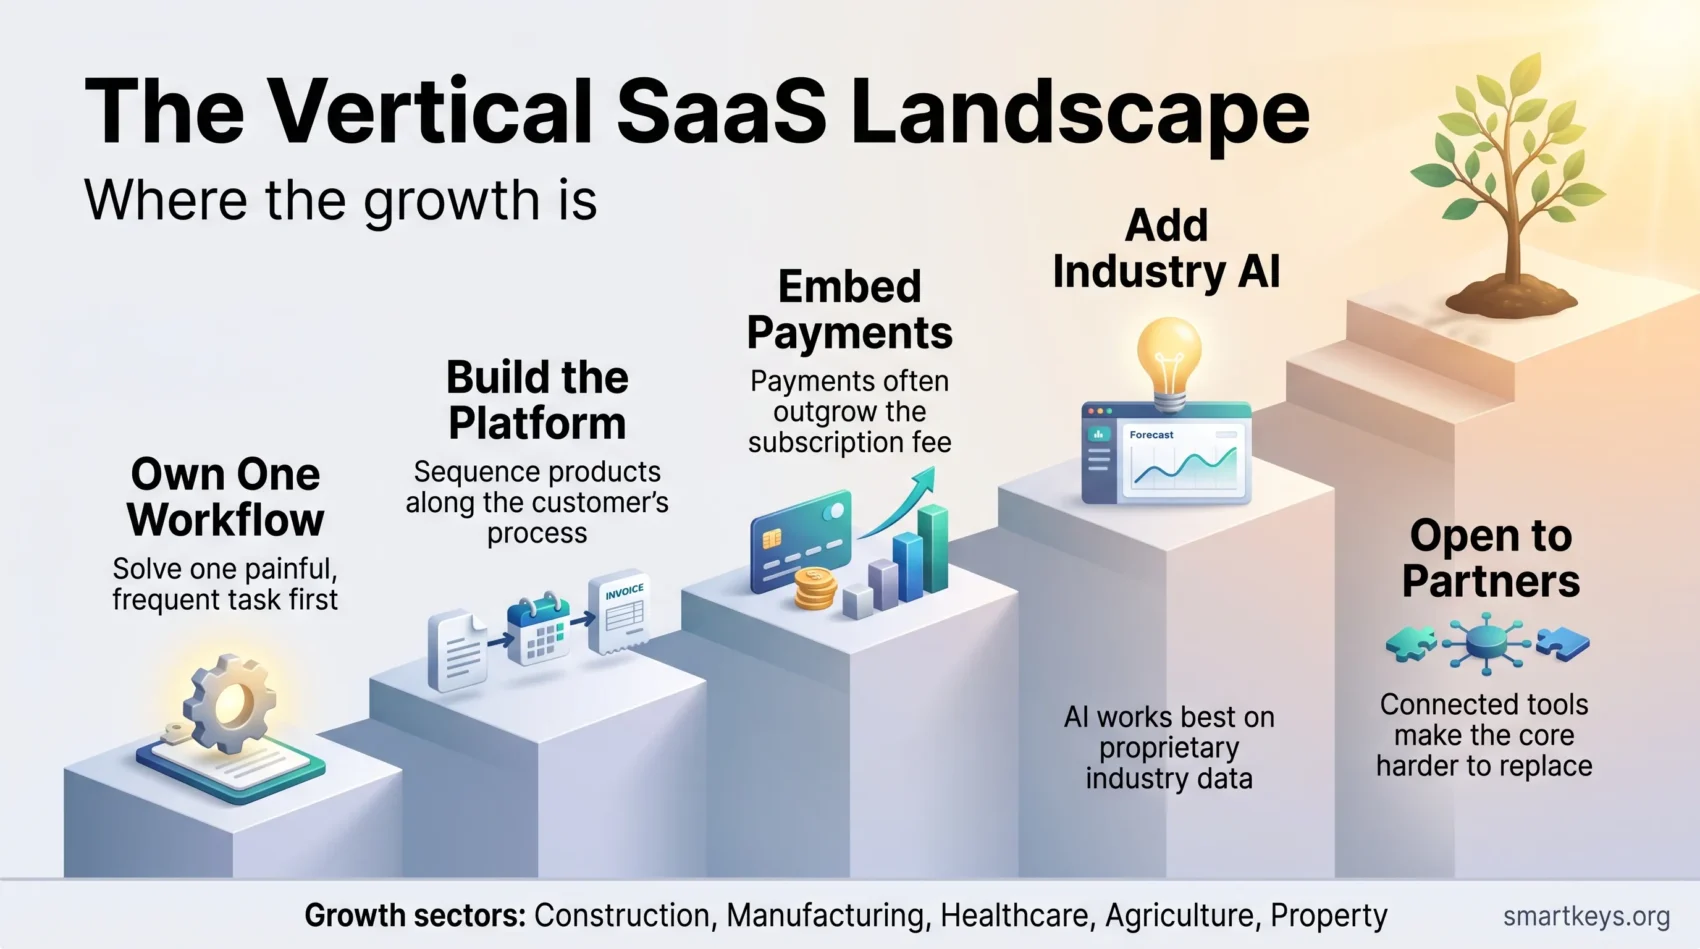
Pick a sector where the current way of working fails often and expensively. Solve one sharp problem well enough that customers pay for it and tell peers about it. Only then add adjacent products.
The reason to start narrow is credibility. Operators can tell within minutes whether software was built by someone who understands their job, and that judgement decides the sale.
Build a platform, then add financial services
Sequence your products along the customer’s actual process: quote, schedule, deliver, invoice, get paid. Once money moves through your software, payments and payouts become a natural extension, and often a larger revenue line than the subscription.
You do not have to become a payments company to do this. Payment facilitation providers, often called payfacs, such as Stripe Connect, Adyen for Platforms or Finix let a software vendor sign up its customers as merchants and earn a share of each transaction. The provider carries the licensing and much of the fraud and compliance work. The trade-off is margin: the more of the payments process you run yourself, the more you keep per transaction, and the more risk and regulation you take on.
Pricing usually shifts as this happens. Vendors move from per-seat fees towards value-based pricing or usage-based pricing, where the bill tracks the work the product does. Getting that transition right is worth its own pricing strategy framework.
Let partners cover the rest
No industry vendor can build every tool its customers need. The stronger ones open their product to other developers instead. Procore, for example, runs an app marketplace where third-party tools for accounting, scheduling or drone surveys plug into its construction platform. Every connected tool makes the core product harder to replace. Industry associations and specialist consultants can play a similar role on the sales side, because they already have the trust of the buyers you want. Building that kind of partner ecosystem deliberately, rather than one integration at a time, is a growth lever in its own right.
Case study: Toast and the restaurant operating system
Toast sells point-of-sale software to restaurants. A point-of-sale, or POS, system is the till: the software that takes the order and the payment. Toast entered a market dominated by ageing hardware and built outwards from that one workflow.
The scale is now substantial. In its second quarter of 2026, Toast reported about 180,000 restaurant locations on the platform, up 22% year on year, with around 9,500 net new locations added in the quarter alone.
How payments changed the revenue mix
The instructive part is where the money comes from. Of Toast’s $1.91 billion in second-quarter 2026 revenue, financial technology solutions accounted for $1.57 billion and subscription software for $290 million. Payments, in other words, are more than five times the size of the software business that made them possible.
Annualized recurring run-rate reached $2.4 billion, up 25%, and gross payment volume, the total value processed through the platform, hit $60.7 billion.
The lesson worth copying
Own a workflow the business cannot run without. Then add the services that naturally sit around it. The software creates the relationship; the financial services monetize it. That sequence, not the technology, is what makes these companies hard to displace.
Case study: Benchling and expansion from a system of record
Benchling began as an electronic lab notebook, or ELN: the digital replacement for the paper notebook scientists use to record experiments. It is an unglamorous, high-frequency task, which is exactly why it worked as an entry point.
Free access for individual researchers built a large base of users and, more importantly, a large base of structured research data. That pulled the product upwards into pharmaceutical and biotechnology companies, where the same notebook had to work across regulated teams.
In November 2021 Benchling raised a $100 million Series F round at a $6.1 billion valuation, co-led by Altimeter and Franklin Templeton, according to Bloomberg’s report at the time.
From notebook to research platform
The company expanded from the notebook into molecular biology tools, sample tracking and development workflows, so that the record of an experiment connects to everything that happens after it.
“Own the record first. The platform is what you build on top of it.”
The transferable idea is that a boring daily task is a better wedge than an impressive occasional one. Frequency creates habit, habit creates data, and data creates the case for the next product.
Sectors to watch in 2026
The niches worth attention share three traits: work that still runs on paper or phone calls, results that can be measured in money, and a workforce that is out in the field rather than at a desk.

Construction
Construction remains one of the least digitized large industries, and the pain is concrete: rework, delays and disputes over what happened on site and when. Software that captures daily field reports, tracks build progress against the schedule and keeps a defensible record has an obvious payback. Raken, Alice Technologies, Doxel and Versatile all work in this space.
Manufacturing
Factories generate enormous amounts of machine data and historically used very little of it. The opportunity is in shop-floor applications, quality inspection and maintenance that is scheduled by condition rather than by calendar. Tulip Interfaces and Instrumental are examples. This is also where digital twins, virtual models of a physical line, are moving from pilot to production.
Healthcare
Healthcare has capacity problems more than technology problems: waiting lists, unfilled appointments and clinicians doing administration. Software that triages demand or predicts bottlenecks helps, but only if it fits the electronic health record staff already use. Curai Health and Qventus are examples. Anything that adds a second system for clinicians to check will fail regardless of quality, which is the recurring lesson of healthcare digital transformation.
Agriculture
Precision agriculture means applying water, seed and chemicals at variable rates across a field rather than uniformly. Sensors, satellite imagery and increasingly autonomous machinery make that practical, and the saving on inputs is easy for a grower to check. Benson Hill, Verdant Robotics and Aerobotics work in this area.
Property and hospitality
Both sectors run on fragmented systems: one supplier for bookings, another for pricing, another for messaging. That fragmentation is itself the opportunity, and it is the thesis behind much of property technology. Canary Technologies and SiteMinder consolidate parts of the hotel stack; Roofstock and Better address different pieces of the residential property chain.
Go-to-market and monetization
Go-to-market, or GTM, is simply how you find, win and keep customers. For industry software it hinges on being specific.
Sell to one buyer, not to everyone
Define a narrow ideal customer profile, the ICP: the type of company you serve best. A dental group with four to twelve practices is an ICP. Healthcare is not. The narrower definition makes marketing cheaper, demos sharper and sales hires easier to train, because they only need to learn one job well.
Trade publications, industry associations and conferences usually beat broad digital advertising here, because the audience is already assembled. Beyond that, the choice between self-serve and a sales team follows the deal size, which is the substance of the product-led versus sales-led debate.
Land, expand, then embed payments
Start with a single repeatable win, then let product usage tell you where to expand. A product-led growth approach works well for the first product because operators can try it themselves, while larger modules usually still need a conversation.
Once transactions run through the platform, embedded payments raise revenue per customer and make switching harder. Set that alongside a clear go-to-market strategy rather than treating it as a late add-on.
What investors expect now
The funding environment has changed the questions founders get asked. Cheap money rewarded growth at almost any cost. Higher rates reward efficient growth, and valuations have come back towards long-run norms.
Two consequences follow. Efficiency metrics now carry the pitch: net revenue retention, which measures how much revenue an existing cohort of customers generates a year later, and the cost of acquiring a customer against the gross profit that customer produces. And exits look different. ServiceTitan, which sells software to home service contractors and was for years the standard private example of a large vertical business, listed on Nasdaq in December 2024 and carried a market capitalization of about $8.8 billion in late August 2026.
Consolidation is now a normal exit
Alongside listings, acquisition by a larger platform has become the common outcome. Buyers use small acquisitions, often called tuck-ins, to add a capability faster than they could build it. Procore’s purchase of Unearth and Zendesk’s purchase of Tymeshift are both examples of that pattern, and it fits the broader move towards SaaS consolidation. Anyone raising money should also read the current startup funding conditions before setting expectations.
Risks and how to reduce them
Specialist software carries real risks, all manageable if you look at them before signing.
Integration work is usually underestimated. A product that fits your industry perfectly still has to exchange data with accounting, payroll and email. Map that data flow during evaluation, not after go-live, and check what the vendor’s API actually supports rather than what the website claims.
Vendor viability matters more here. Industry vendors are often smaller and younger than horizontal ones, and if the product runs a core process, replacing it is painful. Treat the review like an infrastructure decision: financial position, security certifications, customer references and a published roadmap.
You will pay a premium. Specialist products cost more per user than general ones, because the industry knowledge and compliance work are built in. That is defensible if you can point to the hours, errors or penalties it removes. Ask for that arithmetic before the renewal, not during it.
Exit terms are the cheapest insurance. Negotiate data portability in a usable format, a defined notice period and clear ownership of your records. Also confirm where the data is hosted and under which jurisdiction, a question that has become sharper as cloud sovereignty rules tighten.
For vendors, concentration cuts both ways. A small market often means a handful of large customers carry a big share of revenue, so losing one hurts. The industry knowledge that wins deals is also slow to build and hard to hire for. Founders should budget for domain experts early and watch how much revenue depends on their top ten accounts.
Conclusion
Vertical SaaS works because it removes the gap between how software behaves and how an industry actually operates. The market is growing at around 11.5% a year, the successful companies have followed a recognizable path, and the sectors with the most room left are the ones that never fully digitized.
If you are building, start with one painful and frequent task, earn the right to expand, and think about payments early rather than late. If you are buying, judge the product on how closely it matches your process, and judge the vendor on whether it will still be here in five years. Either way, look for the industry-specific workflows that general software forces you to invent yourself.
Found this useful?
Make SmartKeys a preferred source on Google, and our articles will surface more often in your Top Stories, AI Overviews, and AI Mode.
Add as Preferred Source